Published Last updated
Charlotte is one line in a market report and six separate decisions in practice. Here is where our capital goes in this metro, where it does not, and what would have to change for either to move.
Six submarkets, three answers, one metro number that decides nothing
Charlotte is a single line in most market reports and six different decisions in practice. The metro absorbs apartments well and delivers a great many of them, and both of those facts are averages across submarkets that are not behaving alike. An investor who is shown a Charlotte deal is not buying the metro. They are buying one submarket, at one basis, with one delivery schedule in front of it.
So this page does the thing the research reports do not. It states, submarket by submarket, where we would put money in Charlotte today, where we would not, and what would have to change for that to move. Two submarkets we treat as targets, one we avoid on basis, and three we watch for reasons that differ from each other.
Nothing here is an offer, and none of it is advice about your situation. It is our reading, published so it can be argued with.
Uptown and South End: we have not bought here, and the reason is under review
Our published position on Uptown and South End is that we do not buy there, on two grounds: it carries the highest basis in the metro, and it has been the center of the delivery pipeline. Construction employment across the metro was up 8.2 percent over twelve months, and this is where most of that work lands.1
The second of those two reasons is now moving. Q2 2026 reporting has Uptown and South End deliveries falling to roughly half of the prior year's total, with absorption across the metro gaining momentum as the delivery schedule slows.4 If that holds, the supply argument for avoiding the submarket weakens over the next several quarters.
The basis argument does not. A slowing pipeline changes when a submarket clears, not what you paid to enter it, and our objection to the urban core has always been priced entry rather than timing alone. So the honest statement of our position is this: one of our two reasons is weakening, the other is not, and we would rather say that plainly than leave a confident-sounding stance on a page while the ground moves underneath it.
What would move us: entry basis that reflects the concession environment rather than the pre-delivery pricing, and a delivery calendar within two miles that is genuinely clearing rather than pausing. Until both are true, our capital goes to the two submarkets below.
University City: the vintage and the employer are the whole thesis
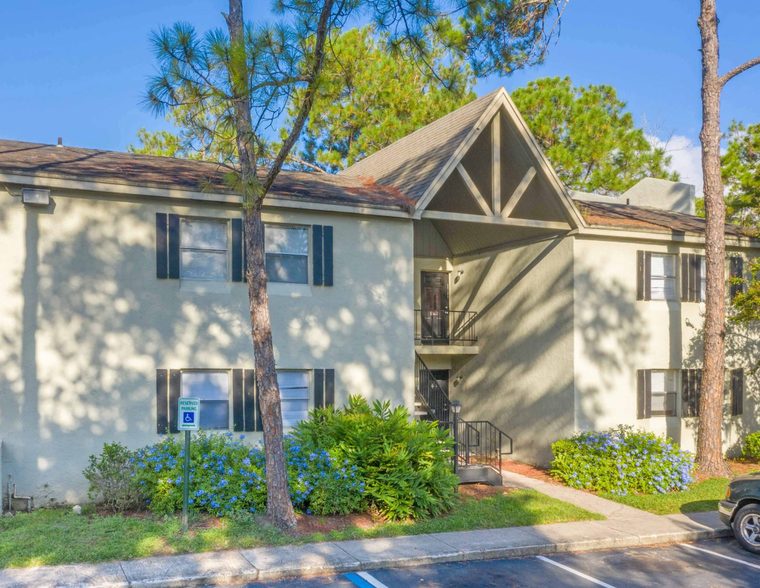
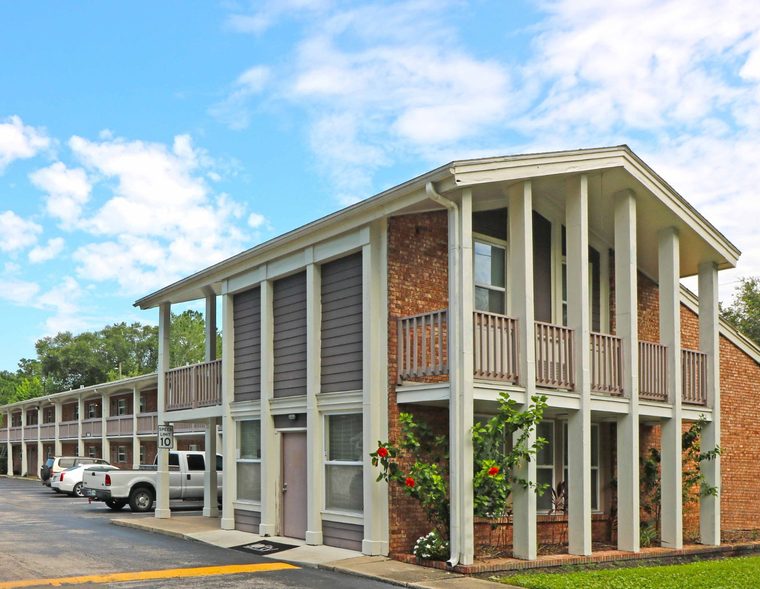
University City is a target for us, and the reason is narrow enough to state in one sentence: 1980s and 1990s inventory sitting next to an employment base that does not leave.
Education and health services employment in the metro grew 2.8 percent over twelve months, and that is the sector anchoring renter demand along this corridor.1 It is the least cyclical demand in Charlotte, which matters more than headline growth when you are underwriting a hold through a delivery window.
The vintage is the other half. New supply competes hardest against product of similar age and price point, so a 1980s or 1990s asset with an established renter base is exposed to the pipeline indirectly rather than directly. That is not immunity. Concessions in new lease-ups reset what renters expect to pay and reach older stock with a lag of a few quarters, which is why we hold rents flat in our Charlotte underwriting until the schedule clears rather than assuming the older vintage is insulated.
Just under half the metro adult population, 49.2 percent, holds a bachelor's degree or higher,2 which is the composition that supports the rent level a value-add plan depends on. You can rebuild that yourself from data.census.gov3 rather than taking it from us.
East Charlotte and the Independence corridor: where the renovation math is a decision, not a filing
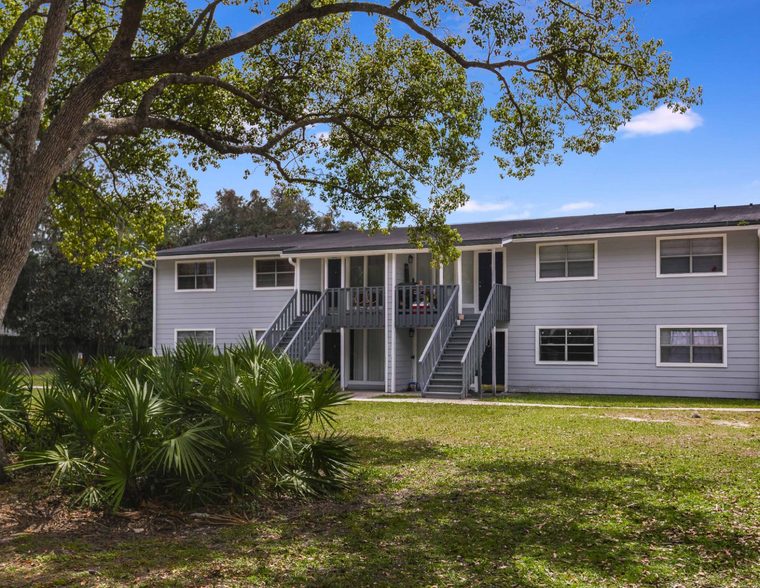
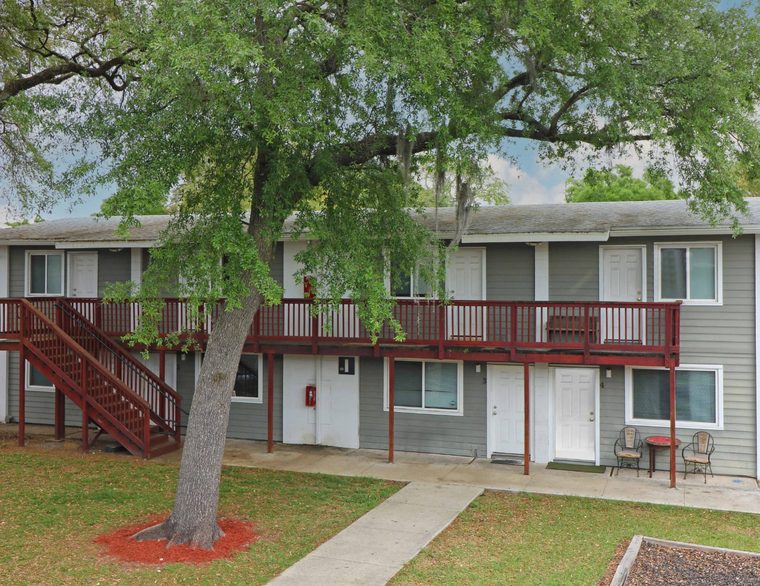
This is the deepest concentration of older garden product at a workforce basis in the metro, and it is our second target.
The structural point is legal rather than economic. North Carolina preempts local rent regulation under General Statute 42-14.1, so no municipality in the state sets what you may charge.5 In a coastal market a renovation premium is a question you answer for a regulator. Here it is a pricing decision you answer for a renter. That single difference removes an entire category of risk from a value-add underwriting, and it is the reason a Charlotte workforce asset and a nominally similar asset in a regulated state are not comparable instruments.
The counterweight sits in the same employment data we use to make the case. Metro manufacturing employment fell 3.0 percent over twelve months and is concentrated on the west side of the metro.1 We treat submarket selection here as a sector question rather than a geography question, which is why we look east for workforce product and treat the western submarkets differently, below.
Three we watch, for three different reasons
| Submarket | Why we are not buying today | What we watch |
|---|---|---|
| Ballantyne and south Charlotte | Incomes and schools are strong and pricing already reflects both | Whether basis dislocates enough to matter, given renters here have ownership options |
| Concord and Cabarrus County | Inside the metro statistical area but a separate county and tax jurisdiction | The county revaluation cycle, because the post-sale tax step-up is modeled separately |
| Gastonia and Gaston County | Lowest basis in the metro, on a manufacturing-weighted payroll | Whether the payroll stabilizes, given metro manufacturing fell 3.0 percent |
Ballantyne is the one most often pitched to investors as the safe Charlotte submarket, and it may well be the most durable. Durability and entry basis are different questions. Countywide median home value is $406,800 and is exceeded substantially in this submarket,2 which means the renter here has a genuine ownership alternative, and that caps what a rent plan can assume.
Gastonia is the mirror image. It carries the lowest basis in the metro, which is exactly what makes it interesting and exactly why we have not bought there. A low basis on a payroll that is contracting is not a discount, it is a forecast.
The three-county problem nobody puts in a market report
The Charlotte metro spans more than one county, and property tax in North Carolina is administered at the county level with each county running its own revaluation cycle.6 Mecklenburg, Cabarrus and Gaston do not revalue in step.
For an investor this is not trivia. Taxes are usually the largest single line an operator can get wrong in year one, because a post-sale assessment can reset to the purchase price, and when that happens depends on which county the asset sits in and where that county is in its cycle. Two assets bought the same month on opposite sides of a county line can carry materially different tax trajectories, and nothing in a metro-level report will tell you that.
It is also the most answerable question on this page. The next scheduled revaluation date and the last three assessed values are public, per parcel, and any sponsor who cannot produce them for an asset they are asking you to fund has not underwritten the largest controllable expense line.
What to ask about a Charlotte asset
- Which submarket is this asset in, and what is the delivery calendar within two miles, quarter by quarter, eight quarters forward?
- Which county administers this parcel, when is its next scheduled revaluation, and what are the last three assessed values?
- What vintage is the competing supply, and is it competing with this asset directly or at a different price point?
- If rents are held flat through the delivery window, does the plan still work, and what happens in year three if they are not?
What this is built on
- U.S. Bureau of Labor Statistics, Economy at a Glance, Charlotte-Concord-Gastonia, NC-SC
- U.S. Census Bureau, QuickFacts, Mecklenburg County, North Carolina
- U.S. Census Bureau, data.census.gov
- Northmarq, Charlotte multifamily market report, Q2 2026 (retrieved 30 September 2026)
- North Carolina General Assembly, General Statute 42-14.1, preemption of local regulation of rents
- North Carolina Department of Revenue, Property tax
- U.S. Census Bureau, Building Permits Survey
-
No question matches that. Try another word, or ask the one that is not on this list.

Ricardo Sanabria · Grey Oaks Multifamily
Answering
Follow-up questions people ask after reading this.
Which Charlotte submarkets does Grey Oaks target?
University City and the East Charlotte and Independence corridor. University City for 1980s and 1990s inventory next to an education and health employment base that grew 2.8 percent over twelve months. East Charlotte for the deepest concentration of older workforce product, where North Carolina preemption of local rent regulation makes a renovation premium a pricing decision rather than a regulatory filing.
Ricardo Sanabria, Grey Oaks Multifamily
Why does Grey Oaks avoid Uptown and South End?
On two grounds: the highest entry basis in the metro, and delivery concentration. As of Q2 2026 the delivery argument is weakening, with Uptown and South End deliveries reported falling to roughly half of the prior year total. The basis argument is unchanged. We treat the position as under review rather than settled.
Ricardo Sanabria, Grey Oaks Multifamily
Is the Charlotte metro vacancy rate a useful number?
Not on its own, and reputable sources currently publish different figures for overlapping periods. The decision-relevant question is the delivery calendar within about two miles of the specific asset, quarter by quarter, because a submarket taking three hundred units in a quarter behaves nothing like one two miles away taking none.
Ricardo Sanabria, Grey Oaks Multifamily
Why does the county matter in a Charlotte deal?
Property tax in North Carolina is administered per county, and Mecklenburg, Cabarrus and Gaston run their own revaluation cycles. A post-sale assessment can reset toward the purchase price, and when that happens depends on the county and where it sits in its cycle. It is the largest controllable expense line and it is not visible in a metro report.
Ricardo Sanabria, Grey Oaks Multifamily
4 questions